
Since the beginning of the year, Treasury yields have risen, lifted by a host of factors, including rising energy prices, stronger-than-expected economic growth, a surge in public and private sector borrowing globally, and a critical shift in both tone and policy from the Fed. This confluence of factors has pushed yields higher despite relatively stable fundamentals.
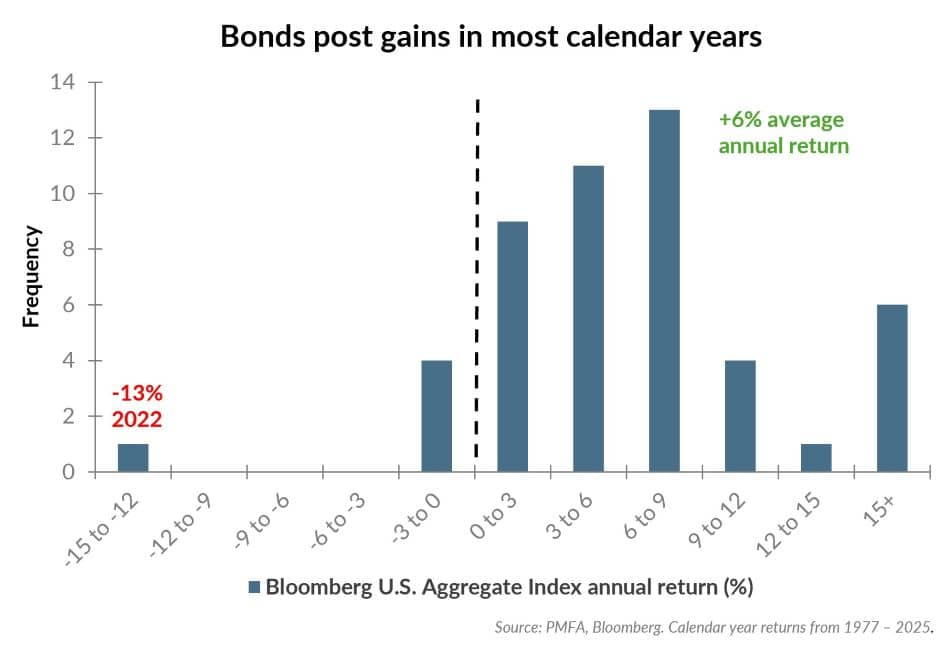
Despite the surge in yields, the Bloomberg U.S. Aggregate Index return is only fractionally negative year to date, illustrating the benefit of higher yields buffering against declining prices. The bigger story that can be easy to overlook may be what today’s higher yields should contribute to future bond portfolio returns. Since 1977, the Bloomberg U.S. Aggregate Bond Index has experienced just five negative calendar years, compared to 34 positive years and an average annual return of roughly 6%. Notably, every negative performance year except 2021 was followed by positive returns over the subsequent three-year period, with episodes like 1994 and 1999 leading to low double-digit annualized gains.
The key difference today is the starting point for yields. Investors entered 2013, 2021, and 2022 with historically thin income cushions. Today, yields across much of the investment-grade bond market sit at levels not seen around two decades — a critical underpinning and natural positive tailwind for bond portfolio return expectations.
Past performance does not guarantee future results. All investments include risk and have the potential for loss as well as gain.
Data sources for peer group comparisons, returns, and standard statistical data are provided by the sources referenced and are based on data obtained from recognized statistical services or other sources believed to be reliable. However, some or all of the information has not been verified prior to the analysis, and we do not make any representations as to its accuracy or completeness. Any analysis nonfactual in nature constitutes only current opinions, which are subject to change. Benchmarks or indices are included for information purposes only to reflect the current market environment; no index is a directly tradable investment. There may be instances when consultant opinions regarding any fundamental or quantitative analysis may not agree.
Plante Moran Financial Advisors (PMFA) publishes this update to convey general information about market conditions and not for the purpose of providing investment advice. Investment in any of the companies or sectors mentioned herein may not be appropriate for you. You should consult a representative from PMFA for investment advice regarding your own situation.


