
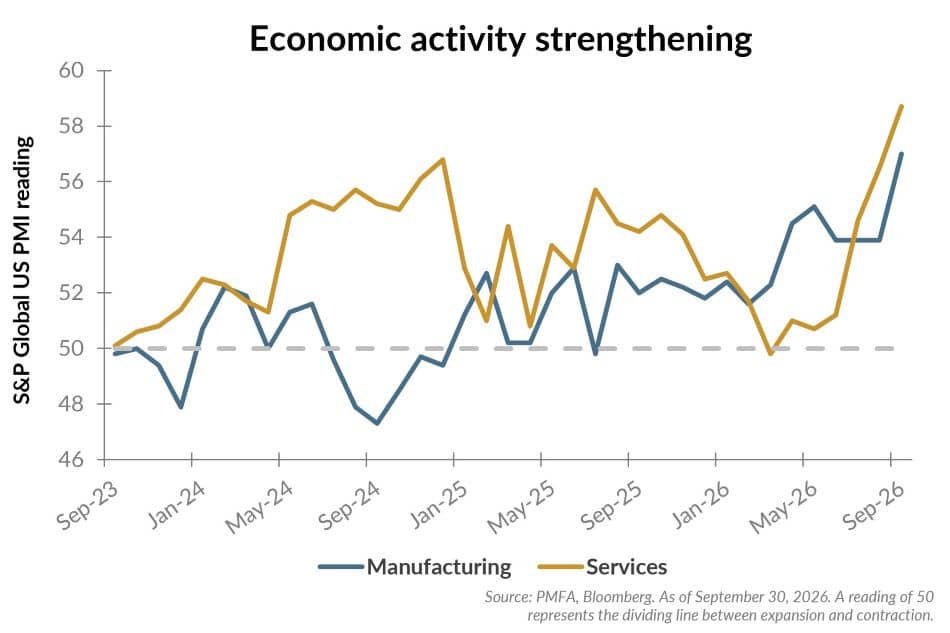
Recently released Purchasing Manager Index (PMI) data showed that activity across both the services and manufacturing sectors strengthened in September, reinforcing the view that the economy continues to expand at a solid clip. (Stronger growth was also validated by the recent release of revised GDP data that sharply increased estimated growth to over 2% in Q2.) In fact, outside of the extraordinary rebound that accompanied the post-pandemic reopening, current business activity is expanding at a pace not seen since the mid-2010s.
The details beneath the headline numbers paint a more nuanced, but still positive, picture. Survey respondents reported stronger demand and increased employment, suggesting businesses remain confident enough to expand capacity. At the same time, companies cited increasing difficulty finding workers, rising order backlogs, and renewed supply chain bottlenecks. Input costs also rose, particularly for energy-related inputs, where price pressures reached their highest levels since late 2022. While stronger activity is encouraging, these trends suggest inflationary pressures remain a challenge.
For investors, the broader takeaway remains constructive. Strong corporate earnings growth has been supported by underlying economic resilience. This combination has contributed to stronger-than-average equity market returns for a midterm election year — an anomaly relative to the historical results in recent decades.
That said, stronger growth doesn't eliminate the potential for market turbulence, as we discuss in our accompanying piece. Historical trends notwithstanding, the surprising resilience of the economy remains a key positive catalyst underpinning the stock market.
Past performance does not guarantee future results. All investments include risk and have the potential for loss as well as gain.
Data sources for peer group comparisons, returns, and standard statistical data are provided by the sources referenced and are based on data obtained from recognized statistical services or other sources believed to be reliable. However, some or all of the information has not been verified prior to the analysis, and we do not make any representations as to its accuracy or completeness. Any analysis nonfactual in nature constitutes only current opinions, which are subject to change. Benchmarks or indices are included for information purposes only to reflect the current market environment; no index is a directly tradable investment. There may be instances when consultant opinions regarding any fundamental or quantitative analysis may not agree.
Plante Moran Financial Advisors (PMFA) publishes this update to convey general information about market conditions and not for the purpose of providing investment advice. Investment in any of the companies or sectors mentioned herein may not be appropriate for you. You should consult a representative from PMFA for investment advice regarding your own situation.


